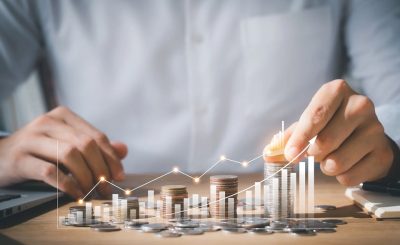
For generations, building wealth was often associated with a familiar formula: earn a stable income, save consistently, purchase property, and invest in conventional financial products. That approach still has an important place in Singapore, but changing economic conditions and evolving financial goals are encouraging more people to think beyond traditional wealth-building methods. Rising living costs, shifting interest rates, technological change, and greater access to global markets have all contributed to a more flexible view of what financial progress can look like.
The modern Singaporean investor is increasingly interested in understanding different ways to manage and grow money rather than relying on a single asset or strategy. This does not necessarily mean abandoning established approaches. Instead, it reflects a broader understanding that financial resilience can come from diversification, informed decision-making, and a willingness to adapt as personal circumstances and markets change.
Changing Attitudes Towards Wealth Creation
Singapore has long had a strong culture of saving and financial planning. Property ownership, CPF savings, bank deposits, insurance, and long-term investments remain central to household financial planning. These approaches can provide stability and support important goals such as retirement, education, and home ownership. However, financial priorities are changing as younger generations face different career paths, higher housing costs, longer retirement horizons, and an increasingly international economy.
Greater access to financial information has also changed how people approach investing. Online platforms, financial education resources, market research, and digital investment services have made it easier for individuals to learn about asset classes that were once less accessible. Investors can now explore international equities, exchange-traded funds, bonds, commodities, and other instruments from their own devices. This convenience has expanded awareness, although it also makes financial literacy and careful research more important.
Another significant change is the growing recognition that wealth building is not simply about finding the investment with the highest potential return. Professional financial advisers and major financial institutions commonly emphasise the importance of diversification, appropriate risk levels, investment time horizons, and maintaining sufficient liquidity. For individuals, this means looking at their entire financial position rather than judging an investment in isolation.
Why Diversification Matters More Than Ever
One reason Singaporeans may be looking beyond traditional wealth-building methods is the desire to avoid excessive dependence on one source of financial growth. Property, for example, has historically been an important part of Singapore’s wealth landscape, but concentrating too much wealth in a single asset class can create vulnerabilities. Diversification allows investors to spread exposure across different assets, markets, sectors, and geographic regions.
International investing can be one way of achieving broader exposure. Singapore’s economy is closely connected to global trade and finance, and investors can access businesses and markets across North America, Europe, Asia, and other regions. A diversified portfolio may therefore contain assets with different economic drivers rather than relying entirely on the performance of the domestic economy.
However, diversification should not be confused with owning as many investments as possible. A portfolio can contain numerous assets while still being exposed to similar risks. Understanding correlations, fees, currency movements, volatility, and investment objectives is essential. Investors should also recognise that diversification cannot eliminate market losses. Its purpose is to manage concentration risk and create a more balanced financial strategy over the long term.
Building a More Flexible Financial Future
Singaporeans looking beyond traditional wealth building are not necessarily rejecting established financial principles. In many cases, they are combining those principles with a wider range of investment possibilities. Saving regularly, controlling debt, maintaining adequate cash reserves, and investing consistently can remain fundamental while additional assets are introduced gradually as knowledge and financial capacity develop.
This broader approach can also encourage people to think about wealth in terms of resilience rather than returns alone. A financially resilient household may have multiple sources of financial security, manageable liabilities, appropriate insurance, diversified investments, and a clear plan for future expenses. These foundations can provide greater flexibility when economic circumstances change.
For those who want to explore additional opportunities, reliable education and careful comparison are valuable starting points. Taking time to visit this website can be part of a wider research process, provided investors evaluate information critically and consider whether any opportunity is appropriate for their individual circumstances. Professional guidance may also be useful when decisions involve substantial sums, complex products, taxation, or long-term financial planning.
Conclusion
The changing wealth-building landscape in Singapore reflects a broader shift in how people think about financial security. Traditional methods continue to have value, but investors now have access to more information, markets, and financial tools than previous generations. This expanded choice makes it possible to create strategies that are more closely aligned with individual goals, time horizons, and risk preferences.
Successful wealth building is less about chasing the newest opportunity and more about making informed, sustainable decisions. Singaporeans who combine established financial habits with thoughtful diversification, ongoing education, and realistic expectations can approach their financial future with greater flexibility.